FIGFCU Business Checking Bonus Offers Up to $1,500 Through December 2026
Businesses can earn $400 to $1,500 by meeting deposit and activity rules. Compare the bonus with the cash you’ll need to keep in the account.
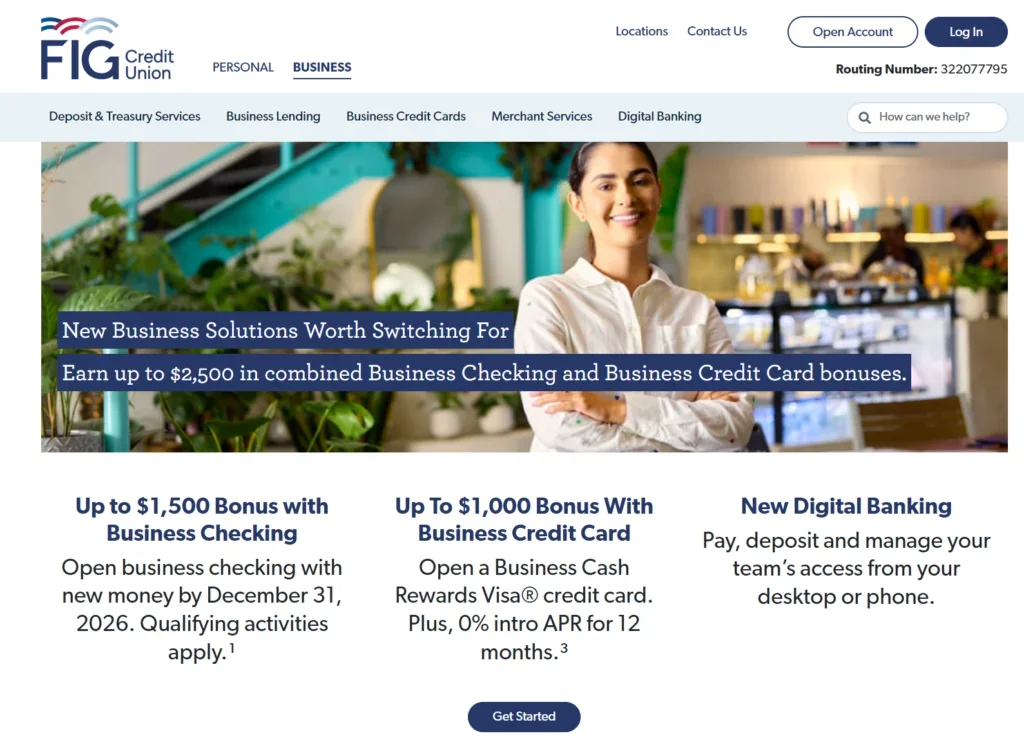
Farmers Insurance Federal Credit Union (FIGFCU) is offering eligible businesses a bonus of up to $1,500 for opening a new business checking account. The top payout requires a $100,000 deposit, while the smallest qualifying deposit, $5,000, earns $400. The deposit must be new to the credit union, stay at the required level through day 90, and be paired with account activity and digital enrollment.
The offer runs from September 22 through December 31, 2026. The available details suggest membership may be open to people who join through the American Consumer Council (ACC), but business account approval and nationwide availability aren’t confirmed. Businesses should check eligibility before moving funds or relying on a particular bonus tier. Review the offer details.
Bonus tiers and the money required
The payout depends on the amount deposited within 30 days of opening and maintained during the period from day 31 through day 90:
| Deposit tier | Bonus | Approximate 65-day return | Effective APY estimate |
|---|---|---|---|
| $5,000–$14,999 | $400 | 10.00% | 54.06% |
| $15,000–$49,999 | $750 | 5.00% | 31.52% |
| $50,000–$99,999 | $1,000 | 2.00% | 11.76% |
| $100,000 or more | $1,500 | 1.50% | 8.72% |
The return estimates assume a 65-day hold and leave out the balance needed while waiting for the bonus to arrive. They’re a way to compare the tiers, not a promised yield: the actual result depends on how much cash the business ties up and for how long. The bonus grows with each tier, but the estimated return falls as the required deposit rises. A business should weigh the additional payout against the value of keeping that cash available for payroll, bills, or other needs.
Deposits can arrive in separate increments during the first 30 days, but each increment must qualify as new money. The credit union defines that as funds not already on deposit there. Moving money from another FIGFCU account doesn’t count. It may also review the account’s activity during the 90 days before a deposit to check whether funds were previously held there and then moved out to qualify.
Activity and enrollment conditions
Within 90 days of opening, the business must complete five qualifying transactions that post to the account. These can be any combination of debit card purchases, ACH debits or credits, incoming or outgoing wires, bill payments, desktop deposits, and mobile deposits. The business must also enroll in online banking and eStatements within that same 90-day window.
There’s no direct deposit requirement listed. That gives businesses several ways to meet the transaction condition, but timing matters: the transactions must post within the qualification period. Keep records of deposits, transfers, posted activity, and enrollment so you can check that each condition is complete before the deadline.
Only one promotional incentive is available per Tax Identification Number (TIN). The business must keep the account open and in good standing until it has met all program requirements. The bonus is deposited into the business member’s Business Membership Savings account up to 45 days after the 90-day qualification period ends. Bonus payments may also be subject to IRS tax reporting requirements.
Account costs and application details
Basic business checking carries a $10 monthly fee. FIGFCU waives it when the account maintains a $5,000 average daily balance. That balance condition is separate from the promotion’s tier requirement, so businesses should check both when planning how much cash to leave in the account. The fee schedule lists no early account termination fee.
The offer information describes the application credit inquiry as a soft pull and says the credit union checks ChexSystems. It also lists credit card funding of up to $1,000. These details may matter to businesses comparing account applications, but they don’t change the offer’s deposit rules or guarantee approval. There’s no household limit listed, and the available information says the $10 monthly fee can be avoided.
FIGFCU may change, pause, or end the program. Its terms say that a change won’t harm the eligibility of a business that opened an eligible account during the promotion period before the change took effect, provided the business meets the applicable requirements. Confirm the current terms when opening, and keep a copy for reference.
Does the bonus make sense for your business?
The $400 tier has the strongest estimated return in the source’s comparison, while the largest bonus requires substantially more cash and produces a lower estimated return. The best fit depends on whether the business can spare the qualifying balance for the maintenance period without disrupting its normal cash flow. A larger headline payout may be less useful if the required deposit needs to stay available for near-term expenses.
One approach described for evaluating the offer is to fund the account near the end of the 30-day deposit window, maintain the required balance through day 90, then reduce the balance to $5,000 to meet the stated fee-waiver threshold while awaiting the bonus. The bonus may take up to 45 days after the qualification period to post, so include that wait in your cash planning. The offer’s terms should guide the timing, especially because the required average daily balance and maintenance period affect the actual cost of holding the funds.
Useful background on account bonuses and application details is available in these resources: a guide to bank account bonuses, direct deposit methods, account inquiry types, and credit card account funding.

The offer may be worth considering for a business that meets the membership rules, can keep the needed balance in place, and is comfortable completing the activity steps. Before applying, verify that the business qualifies and match the tier to cash the business can leave deposited through the full maintenance and bonus-payment timeline.